
This campaign season, Post editor Kyle Palmer has extended one-on-one Q&A offers to all candidates running for statewide offices, including U.S. Senate, Governor, Attorney General, Secretary of State, Insurance Commissioner and Kansas State Board of Education.
We will publish videos of Kyle’s full interviews and an edited transcript of his conversations as each candidate responds.
SHAMELESS PLUG
No other news outlet devotes as much attention to giving Johnson County voters a way to find out where candidates running for local office stand on the issues important to our community. If you value having a news outlet provide this kind of coverage, consider becoming a subscriber if you aren’t already. Try us out for just $1/week.
A whole raft of statewide offices is on Kansans’ ballots on Nov. 3, and you’ve likely been following some of them, including the tight U.S. Senate contest and the race for governor.
But just down the ballot from those races is the state insurance commissioner contest. That includes Democratic candidate Dinah Sykes, currently a state senator from Lenexa, running against Republican House Speaker Dan Hawkins. Libertarian Rick Koehn also in the race.
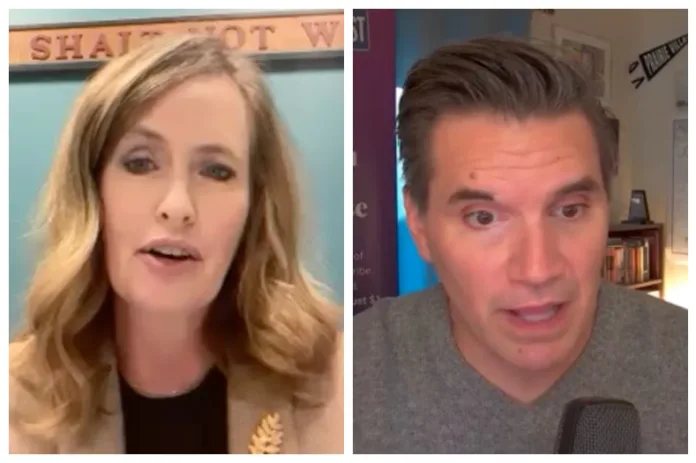
Sykes spoke with Post editor Kyle Palmer via Zoom on Thursday, Oct. 22.
Post: This office is not as talked about as some of the other races on the ballot this year. In plain terms, what does the insurance commissioner do, and why should a Johnson County homeowner or car owner or someone who deals with health insurance, why should they care who wins?
Sykes: I think this is probably the most overlooked race on the ballot, and it is so important to your everyday lives. Kansas is one of 11 states that elect their insurance commissioner, and they are the regulator of all insurance. So their number one job is making sure that insurance companies who want to do business [here] have the financial backing and that they are solvent. It’s also the [office] that licenses any agents. But the big part about why consumers should care is that it is a consumer protection office. So consumers are paying for their policies. It doesn’t matter if it’s auto, life, home, health, property or casualty. All of those are under the insurance commissioner. So I tell people you can’t drive a car, own a home, rent a home or work in Kansas without the Kansas Insurance Commissioner’s office affecting your daily life.
Post: You’ve been in the Kansas Senate now for a decade. You originally came in as a Republican. You switched parties. You’ve now been Democratic leader in the Senate for at least six years. So why do you want to leave that job for this one?
Sykes: So I have loved serving as a senator, but a lot of the issues that I have dealt with have been helping my constituents with claims on insurance, helping them navigate that process. So I really think I have a bigger platform. I love solving problems. My background is in finance and accounting, and I am a data wonk. So this really helps me. Health insurance has been in the news a lot recently, especially with subsidies going away. We know the system is broken, and I think my track record in the Senate of bringing people together to solve problems for Kansans will actually be an asset because I think Kansans are smart. We can do difficult things, but it’s going to bring people to the table to have these discussions and find a solution. I think I go back to that William Allen White saying, you know, if it’s going to happen, it’s going to happen in Kansas first, and I think we can lead the nation.
Post: Homeowners have watched premiums climb year after year. I believe it was the Wichita Eagle that reported that home insurance rates in Kansas have risen steeply, more than 40% since 2020. There are natural threats like hail and tornadoes and severe thunderstorms and flooding. What can the insurance commissioner realistically do about that? What’s your plan for dealing with rising home insurance rates?
Sykes: I’ve already had some conversations. I told you I’m a data nerd. I’m digging in. How do we compare with others? We actually have fewer claims than a lot of surrounding states, but higher premiums. And we need to look into this data. What is the amount that people are paying out? How do we bring more competition in? I actually talked to someone just this week who was dealing with insurance for cattle. My dad raised cattle, so it was actually something that I care deeply about, but they were like, ‘You know, we have a friendly environment in Kansas, and as I’ve looked, Iowa has a lot more carriers in Iowa,’ and I was like, ‘Why did you not go to Iowa? You know, what are the benefits?’ They’re like, ‘They actually have a backlog now, so I think that gives Kansas an opportunity of bringing more carriers to have more competition.’ But also really looking at what those chokeholds are that are causing problems. Again, on the consumer protection side, insurance is complicated, but we need to help Kansans and consumers be able to evaluate those policies. As I’ve sat down with people who lost in the Wyandotte storms, looking at their policies, they’re asking, ‘Is my roof covered? Is it not?’ And those are things that, when you’re looking at those policies and trying to sign up for what you think is best for you and your family, we need to make sure that they have all the tools in there available to make sure they’re making those informed decisions.
Post: Is there anything that the state can do to make insurance more transparent for users, whether it be for home insurance or even health insurance, which is a whole other ball of wax? Is there anything the state can do to make that an easier process, like you were referring to?
Sykes: I have loved traveling the state, talking to policyholders and providers, all that, trying to see what things we could do better, and actually talking to NAIC (the National Association of Insurance Commissioners). They would love to partner with us to help us boost that education for consumers. This is a time [of year] where people are looking at health insurance and trying to decide, even through their employers, about what plan they’re going to get. We need to make sure that they have all of those resources, but also, you know, looking at what do we currently get out to people? Where are those trusted sites to go? I know we have counselors across the state, not enough of them, but how could the insurance commissioner’s office work with them to boost that? Talking to aging and community services, going out to Rotary clubs. There’s a lot of work that we can do that’s just grassroots, helping people have more of those resources and also boosting what is available on the website for the insurance commissioner.
Post: Health insurance is one of the key ones that people often don’t think about until they need it, or if they lose it for some reason or another. Is there anything the state can do for people who might be struggling to find health insurance? Maybe they don’t qualify, maybe they get kicked off a plan. I know there are ever-changing circumstances with the federal marketplace. What can the state do for those circumstances?
Sykes: It is a complicated issue, but I think even with Children’s Mercy right now, and some of the stories that are being highlighted because the subsidies on the ACA are going away, and then those providers not having in-network [coverage], I think there’s a lot of conversation. I think there are a lot of people who can come to the table, and we can look at how we can provide better. When you do have that denial, the insurance commissioner should be someone that you can call, and they can help you go through that process. Sometimes it is a call from the insurance commissioner who actually helps open those doors so that you can get a service. But at the end of the day, we need healthy Kansans in those pools. We need more people being able to have access to primary care, so that we’re not forcing individuals to wait until it is that crisis and they’re going to the ER because that’s more expensive for them. It’s more expensive for our hospitals, and it’s also more expensive for those who have private insurance. So there is a lot that can be done, but it’s going to have to have everyone coming to be a part of this. I truly believe that insurance companies are there to help families have access to care. I think it is shifted, and because we’re always looking at profit, we want them to be successful, but we also want to make sure that they are delivering on those policies.
Post: Your opponent, Republican Speaker [Dan] Hawkins, also says Kansas lacks competition in the insurance market. You alluded to that in one of your earlier answers. He’s in favor of easing regulations, bringing in more insurers. Ultimately, he says that will lower the prices. Is he wrong? How would your approach be different?
Sykes: I think probably looking at regulations. I’m going to make sure that Kansans are protected, and in the Legislature, our records have been very different. I have always sided on the side of consumers and access to care, whereas he has tried to stop prescription drug transparency. He has said no to screenings, diagnostic imaging for mammograms, hearing aids for kids. So he has always sided with profits. So we want competition, and we want to make sure we have a good regulatory market for them. But we also have to make sure that balance is there, that we are looking out for Kansans.
Post: Dan Hawkins has worked in the insurance industry as an agent. Has also owned his own agency. He’s been in the industry for decades. Some people would see that as an asset. I mean, in a race like this, like you said, where there’s not a lot of attention, maybe a biography like that will sound good to voters. So respond to that: Your differing levels of experience with insurance. Make your case for why you would be more qualified for this job than someone who’s been in the industry for 30-plus years.
Sykes: So actually, Kansas law says that with the insurance commissioner, the only tie to the industry should be that they are a policyholder, and he has taken that as his livelihood. You look at his substantial interest. He has a lot of profit from insurance companies. Again, I am not taking a penny from insurance companies. I think Kansans deserve an independent voice. I’m someone who is looking out for them, not a fox guarding the hen house.
Post: You mentioned you did not take donations from the insurance industry. I know there was an issue reported by the Kansas News Service where you had a $1,000 donation, I believe, from the Kansas Association of Property and Casualty Insurance, which is an advocacy group. But that has since been returned. So explain that, just in case someone might have heard about that regarding your pledge to not take donations.
Sykes: So we did. We had a check, and it was whatever the initials K-A-P-C, or something. So my treasurer had it deposited, and then when we found out it was from this property and casualty insurance advocacy group, we returned it immediately as soon as we discovered that.
Post: If you win, what’s the first thing that a Kansan would notice is different about the insurance industry, the insurance department in Kansas? What’s one thing you want them to notice in your first year on the job?
Sykes: My first thing is sitting down and talking to every employee in the insurance commissioner’s office and finding out what is working, what isn’t working. Also, continuing a statewide tour. But I saw a bumper sticker as I’ve been traveling that said, “Please don’t hit me. I don’t understand insurance.” I want to make sure that Kansans have a better understanding of insurance, and we’re making it more relatable to everyday Kansans.
 Thanks for reading! If you value having an independent news outlet keeping tabs on local government, schools and taxes, we're asking you to contribute to our Education Reporting Fund.